One of the most common questions I see asked in self-directed investor forums goes something like this: “Can I pay my kid for doing chores so they have earned income to fund a Roth IRA?” I completely understand the instinct. The Roth IRA is one of the most powerful tax-sheltering tools available, and wanting to start one for your child as early as possible is genuinely smart thinking. However, the answer to that question is an unambiguous no. Household chores — taking out the trash, washing dishes, mowing your own lawn — do not create earned income under IRS rules. The only reliable path to funding a child’s Roth IRA from family money is a real trade or business in which the child performs actual, documentable work. That is the line I want to draw clearly at the outset, and then spend the rest of this post on the practical question you actually came here to answer: which home businesses that can pay your kids legitimately exist, and what jobs can a child plausibly do in each one?
The stakes are worth understanding before we dive into the business types. For 2026, a child can contribute up to $7,500 to a Roth IRA — but only up to the amount of their earned income for the year. So if your ten-year-old earns $3,000 packing and labeling orders for your e-commerce business, they can contribute up to $3,000. A child whose total income stays under their standard deduction owes no federal income tax at all. For 2026, a dependent’s standard deduction is the greater of $1,350 or their earned income plus $450 — so a child earning $3,000 has a standard deduction of $3,450, meaning zero federal income tax on those wages. The parent’s business simultaneously deducts those wages as a legitimate business expense. That combination — tax-free income for the child, deduction for the parent, and decades of Roth compounding ahead — is genuinely hard to beat. But it only works if the business arrangement is real. Let me walk you through which businesses make that possible.
Disclaimer: Everything here is general educational information, not personalized tax or financial advice. Family payroll arrangements have real legal and tax consequences. Please run your specific situation past a CPA before putting anything in place.
Types of Home Businesses That Can Pay Your Kids Legitimately
The IRS does not publish a list of approved business types. What it cares about is whether a real business exists, whether real work was performed, and whether the pay rate is reasonable. That said, certain business models that operate out of a home lend themselves particularly well to age-appropriate child employment. Here are the five categories I think are most practical.
1. Rental Property Businesses
If you own rental property — even a single unit — you are likely operating a trade or business, and there is a surprising amount of work a child can do. Turnover between tenants is the most obvious example. Cleaning, sweeping, wiping down surfaces, removing trash left behind — a twelve-year-old can do all of that competently. Grounds upkeep, such as mowing, weeding, and raking common areas, is appropriate for a ten-year-old and older. Photography for listings is another real task: a fifteen-year-old with a decent smartphone can photograph units for Zillow or Apartments.com, and that work has genuine market value. Even a younger child can help with simple tasks like sorting hardware supplies or labeling storage boxes in a maintenance closet.
The key is to pay a rate you would actually pay a stranger. Turnover cleaning might run $15–$20 per hour in your market. Lawn care might be $25 for a small property. Document the hours, pay by check or direct deposit into the child’s own account, and keep the timesheets. That documentation is everything if questions ever arise.
2. E-Commerce and Product-Based Businesses
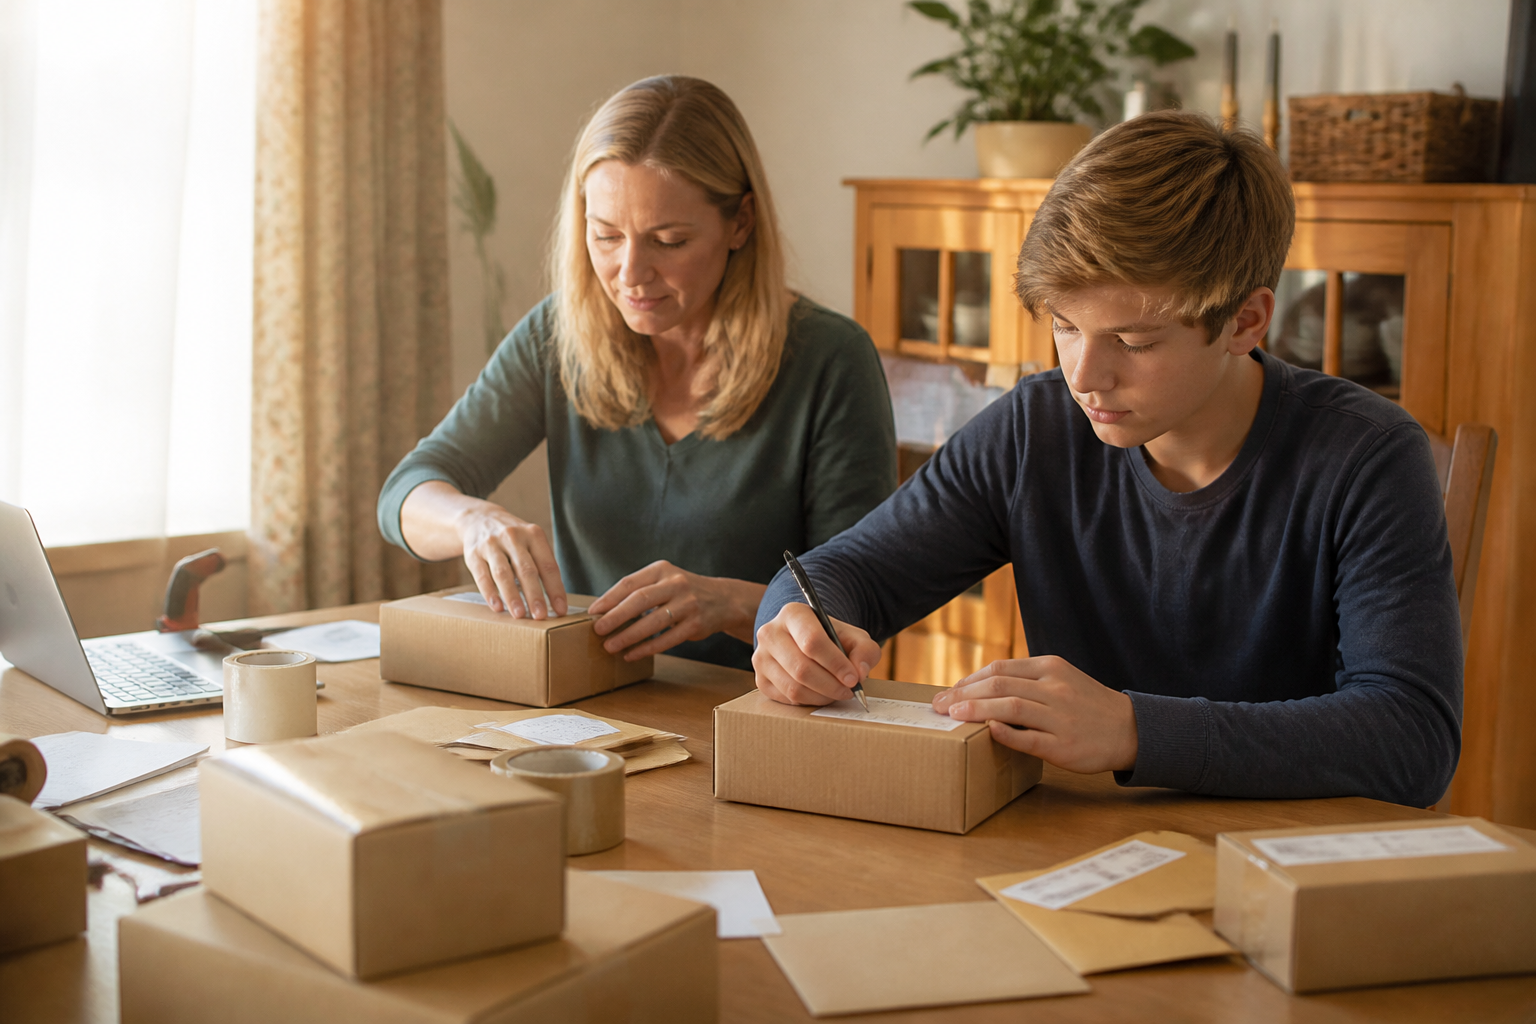
If you sell physical products online — through Etsy, Amazon, eBay, Shopify, or a similar platform — you have one of the cleanest setups for hiring your child in your business. Packing and shipping orders is straightforward, repetitive, and completely defensible. A ten-year-old can fold boxes, stuff tissue paper, affix labels, and prepare packages for carrier pickup. Inventory counts are another legitimate task: walking the shelves and counting units on hand is real work that businesses pay for. Product photography, for older children and teenagers, is increasingly valuable — well-composed product shots directly affect sales, and a fifteen-year-old with an eye for it can produce work worth paying for at market rates.
Specifically, think about what a fulfillment center employee does. They pack, label, count, and move inventory. Your child doing those same tasks in your garage or spare room is doing the same job. Pay them accordingly — $12–$15 per hour is a defensible rate for packing in most parts of the country. Keep a simple log: date, hours worked, task completed, amount paid.
3. Consulting, Freelance, and Service Businesses
This category covers a wide range of home businesses: marketing consultants, bookkeepers, copywriters, web designers, coaches, and anyone else who sells their expertise. These businesses generate a lot of administrative work that a child can legitimately handle. Filing and organizing documents — physical or digital — is appropriate for a ten-year-old. Data entry into spreadsheets or CRM software works well for a twelve or thirteen-year-old. Scheduling, calendar management, and sending confirmation emails can be handled by a fifteen-year-old who has been trained on your systems. Basic bookkeeping tasks, like reconciling receipts against a spreadsheet, are reasonable for a sixteen or seventeen-year-old.
The work has to match the child’s actual capability. A plausible hourly rate for administrative support in this category is $12–$18 per hour, depending on complexity and your local market. In my experience researching these arrangements, the consulting business structure is one people overlook — they assume their solo service business is too small. However, if you are filing a Schedule C, you have a business, and the rules apply.
4. Photography, Creative, and Content Businesses
If you run a photography studio out of your home, sell stock photos, produce content for brands, or operate any kind of creative business, your children may have more earning potential here than anywhere else. Modeling for product shots or stock photography is legitimate paid work — professional child models command real rates, and when your business needs a child model, hiring your own child at a market rate is entirely appropriate. A six-year-old can model for children’s clothing photos. A child of any age can appear in lifestyle shots if your business produces them.
Beyond modeling, older children can handle equipment: setting up backdrops, organizing props, managing lighting stands, and packing gear for location shoots. These are real production assistant tasks. A fifteen-year-old who helps you set up and break down for a shoot is doing work worth $15–$20 per hour in most markets. As with every category, document each session — the date, what was shot or assisted, how many hours, and what was paid.
5. Small-Scale Farming and Home Food Businesses
If you sell produce, baked goods, preserves, honey, eggs, or other food products — at a farmers market, through a CSA, or online — your children can participate in ways that generate real earned income. Packing and labeling jars or containers is appropriate for a ten-year-old and older. Staffing a market stall — greeting customers, making change, bagging purchases — is realistic for a twelve or thirteen-year-old with some supervision. Helping with harvesting, washing, and sorting produce is age-appropriate across a wide range. These are not abstract tasks; they are the same jobs that farm stands pay seasonal workers to do.
Pay rates in agricultural and food-production contexts tend to run $10–$15 per hour for basic labor. Whatever rate you use, make sure it reflects what you would actually pay someone outside the family for the same work.
Family Business Jobs for Kids: What Makes the Arrangement Hold Up
Knowing which business types work is only half the picture. The other half is making the arrangement defensible. There are three things that matter above everything else.
- The work must actually be performed. This sounds obvious, but it is where arrangements collapse. The child has to do the task, not just be listed as doing it. If you cannot describe what your child did, when they did it, and how long it took, the deduction is indefensible.
- The pay rate must be reasonable. You need to pay your child what you would pay a stranger for the same work. Paying a ten-year-old $50 per hour to pack boxes is not defensible. Paying $12–$14 per hour is. Check what platforms like Indeed or Glassdoor show for comparable tasks in your area and document that research.
- The money must actually move. Money announced but never paid — or immediately reclaimed — is the classic failure point. The wages must leave your business account and arrive in your child’s own account. A custodial checking account that the child actually owns is the right vehicle. From there, the child (or you on their behalf) can contribute eligible amounts to a custodial Roth IRA.
Keep a timesheet for every pay period. Note the date, the task, the hours, and the rate. Pay by check or bank transfer — cash is harder to document, though not impossible if you record it carefully. Store those records somewhere you can find them in three years if questions arise.
The Tax Structure You Need to Understand Before You Set This Up
The payroll tax treatment depends on your business structure, and this is one of the most frequently misunderstood pieces. Here is how it actually works.
If your business is a sole proprietorship, or a partnership in which every partner is the child’s parent, wages paid to a child under 18 are exempt from Social Security and Medicare (FICA) taxes. Wages paid to a child under 21 in those same business structures are exempt from Federal Unemployment Tax (FUTA). That exemption is significant — it means both you and your child avoid payroll taxes that would otherwise apply.
However, if your business is organized as a corporation — including an S-corp — or as a partnership that includes any partner who is not the child’s parent, those exemptions disappear entirely. FICA and FUTA apply at any age. This is a real structural consideration, and it is one reason to talk to a CPA before you set anything up. Some business owners restructure specifically to access the exemption; others decide the payroll taxes are worth paying anyway given the other benefits.
As for income tax: a child whose earned income falls under their standard deduction owes no federal income tax. For 2026, that means earned income up to roughly $3,050 is tax-free (the formula is earned income plus $450, so a child earning $3,000 has a $3,450 deduction). Confirm current figures at irs.gov — these numbers adjust with inflation. The 2026 contribution limit for a Roth IRA is $7,500 (verify at irs.gov before contributing). A child who earns $7,500 and deposits it all into a Roth IRA while paying zero federal income tax on it has created a genuinely remarkable outcome.
How to Pay Your Child Through Your Business Roth IRA Strategy: Keeping Clean Records
When I was researching how to structure this kind of arrangement, the single biggest gap I found in available resources was not information about which businesses qualify — it was practical guidance on the record-keeping itself. The IRS does not publish a worksheet for family payroll. Most accounting guides are written for businesses with multiple employees. That gap is why I want to specifically recommend the Hire Your Kids Record Book: The Complete Record-Keeping System for Parents Who Hire Their Kids ($27.99).
This is a purpose-built record-keeping system designed specifically for the family employment scenario. It walks through timesheets, pay records, and the documentation trail that makes this arrangement defensible. I have not seen another resource that addresses this specific need as directly. For a $27.99 investment that protects a multi-year tax strategy, that is an easy call.
As a complementary resource, 475 Tax Deductions for Businesses and Self-Employed Individuals is worth having on your shelf. It covers the broader universe of business deductions, which is useful context when you are integrating a child employment strategy into your overall tax picture.
Who This Strategy Works Best For — and Where It Does Not Fit
This approach works best when a real home business already exists, or when you are genuinely building one. It is not a strategy you can bolt onto a household that has no business income. The business must be real, the work must be real, and the pay must be real. If all three of those conditions are met, the tax benefits are substantial and entirely legal.
It also works best when the child is old enough to perform work that has genuine market value. A six-year-old modeling for product photos is a legitimate scenario. A six-year-old doing “consulting” for a hundred dollars an hour is not. Match the task to the child’s actual capabilities, and document why the rate is reasonable.
This strategy does not work for W-2 employees who have no business of their own. It does not work for parents who want to compensate children for household responsibilities. It requires ongoing maintenance — you cannot set it up once and ignore it. Every pay period needs a timesheet, a payment, and a record.
Final Thoughts on Home Businesses That Can Pay Your Kids
The combination of legitimate child employment, a custodial Roth IRA, and decades of tax-free compounding is one of the most powerful family wealth-building strategies I have come across in my years of managing my own retirement accounts. However, the emphasis on “legitimate” is not optional — it is the entire foundation the strategy rests on. The home businesses that can pay your kids are not exotic or obscure: rental property, e-commerce, consulting, creative work, and food businesses all qualify when structured correctly. What separates the families who benefit from this strategy from those who create a tax problem is documentation, reasonable pay, and money that actually moves.
Here is a quick summary of the key points to keep in mind:
- Household chores are never earned income — a real business is required
- The 2026 Roth IRA contribution limit is $7,500; contributions cannot exceed the child’s earned income
- A dependent’s 2026 standard deduction is the greater of $1,350 or earned income plus $450
- Sole proprietorship and parent-only partnerships are exempt from FICA for children under 18 and FUTA for children under 21
- Corporations and partnerships with non-parent partners owe all payroll taxes regardless of the child’s age
- Work must be performed, pay must be reasonable, and money must actually transfer to the child’s account
- Timesheets and payment records are non-negotiable
- Confirm current limits at irs.gov before contributing for any tax year
Run the specifics of your arrangement past a CPA before you start running payroll. The strategy is well-established and entirely legal — but the details matter, and a professional who knows your business structure can help you get them right.
Frequently Asked Questions
What types of home businesses can you pay your kids through to fund a Roth IRA?
Rental property businesses, e-commerce businesses, and consulting or service businesses all allow legitimate child employment. The IRS doesn’t publish an approved list—it cares whether a real business exists, real work was performed, and pay is reasonable. Tasks like turnover cleaning, packing orders, inventory counts, and administrative work are age-appropriate options that create documentable earned income.
Can a parent pay a child for chores to have earned income for a Roth IRA?
No. Household chores like taking out trash, washing dishes, or mowing your own lawn do not create earned income under IRS rules. The only reliable path to funding a child’s Roth IRA is a real trade or business where the child performs actual, documentable work for reasonable pay rates you’d pay a stranger.
What can you pay your child to do if you hire them in your business?
In rental properties, children can do turnover cleaning, grounds upkeep, and photography. In e-commerce, they can pack orders, count inventory, and take product photos. In service businesses, they can file documents, enter data, manage schedules, and handle basic bookkeeping. All tasks must match the child’s capability and be paid at market rates with documented hours.
How much can you pay your child working in your home business?
Pay rates should match what you’d pay a stranger doing the same work. Turnover cleaning runs $15–$20 per hour, lawn care might be $25 for a small property, and packing is defensible at $12–$15 per hour. Administrative and data entry work typically ranges $12–$18 per hour. Keep timesheets and pay by check or direct deposit into their account.
About This Article
Written by Jennifer Walsh. Jennifer Walsh isn't a financial advisor — she's spent more than 20 years personally managing her own retirement accounts and obsessively optimizing her own Roth conversions and tax strategy. She writes to demystify complex financial concepts so everyday investors can make confident, informed decisions, with no products to sell and no commissions behind her recommendations. More about this site.
Scope and limits. Jennifer is not a financial advisor or tax professional, and nothing here is personalized advice. Retirement and conversion rules change and depend on your own situation — confirm with a CPA or fiduciary advisor before you act.
Verify this against a primary source
Specifics change, and your situation may differ from the one described here. These are the authorities worth checking directly:
- IRS — contribution limits, conversion rules and current publications
- Social Security Administration — benefit timing and taxation of benefits
- FINRA — investor education and fee comparison tools